Tag: Investment Analysis

  • Disrupting supply chains [Hanza AB]

    About Hanza

    Hanza is an contract manufacturer. Hanza is unique due to its cluster manufacturing model. Hanza clusters manufacturing technologies like electronics, machining and assembly in European regional hubs.

    Hanza acquires customers by offering business consulting services [Manufacturing solutions for Increased Growth and earnings – short MIG]. A 4–8-week business analysis of companies’ production process designed to streamline their manufacturing chain https://hanza.com/mig-advisory-services/ . Further, Hanza acquires customers by cross selling supply chain technologies and through acquisitions.

    Hanza creates value for its customers largely by reducing complexity. The relentless focus on efficiency [just in time principles] and globalisation, has introduced highly fragile and fragmented supply chains. By clustering manufacturing in regions, Hanza reduces supply chain risk and increases efficiency.

    For context, In todays business environment, manufactures have lost leverage over intermediaries [since the industrialisation, 1800’s]. In supply and value chains, the dynamics are always changing. The bull thesis, stands largely on a changing geopolitical environment -> that improves the value proposition of regional cluster manufacturing contrarian to fragmented arms-length supplier relationships.

    Applying an ARA-model

    This section aims to explore how geopolitical trends are affecting the OEM and manufacturer relationship.

    In recent years; the Suez and Hormuz canal, corona lock downs and tarifs have severely affected supply chains. These geopolitical risks geopolitical risks has increased the value proposition for near shoring. This changes the linked layers in the ARA model significantly.

    Activity Layer

    When the operational processes of different actors are coordinated, they form activity links. This includes synchronized production schedules, joint R&D efforts, or integrated logistics.

    HANZA pools machinery and talent, by grouping multiple manufacturing technologies into regional clusters. This generates capabilities and economies of scale, individual companies would struggle to achieve on their own. HANZAs contract manufacturing and value chain consultancy, integrates customers and creates a sticky business model.

    Resource layer

    The model assumes resources are heterogeneous; their value is not fixed, but depends entirely on how they are combined. When the assets of one actor are specifically adapted to fit the assets of another, they form resource ties (e.g., a company customising its software to directly read a supplier’s database).

    OEMs are increasingly dependent on manufactures to manage increasingly fragile, complex, fragmented and global supply chains. Broadly speaking firms no longer save resources by applying just in time and fragmented supply chains, as the risk of these fragile supply chains breaking, significantly affect the expected value of such actions. Furthermore, highly specialised technology like microchips, serve as impenetrable barriers.

    Actor layer

    Actors form bonds with one another through trust, legal contracts, and historical interactions. These bonds determine the level of friction, knowledge sharing, and strategic alignment in the network.

    Changes in the actor layer are illustrated by the changes in the manufacturer-OEM relationship. Firms like Hanza are increasingly capturing more of the supply-chain, by offering services traditionally governed by intermediaries. Across business units, Hanza is capable of managing the full supply chain – and take on the risk involved. OEMs are thus increasingly innovation and marketing houses closely integrating with manufacturers.

    note

    The ARA model has inherent strengths and weaknesses. The model can reveal hidden moats by examing switching costs, it highlights co creation by recognizing that competetive advantages often stems from external partnerships and it highlights this interdepencence and how changes can cascade. But, the model is descriptive, it assumes bounded rationality where actors optimize for efficiency and it is blind to actors outside the network.

    Transaction Cost Theory

    Transaction Frequency

    Uncertainty

    Asset Specificity

    Applying Porters Five Forces

    – Threat of new entrants. Manufacturing is highly competitive. The clustering approach is replicable. But it does require capital, capabilities and customers. Regional hubs must be placed in areas with plenty of access to transportation, labor, electricity etc., putting natural barriers to entry. Low.

    – Bargaining power of suppliers. The cluster model relies on technological advanced parts like semiconductors and robotics. These suppliers have leverage over Hanza. High.

    – Bargaining power of buyers. Initially it’s high. The customer has an existing value chain that they might wish to improve. As the customer becomes integrated with Hanza, the bargaining power shifts and becomes low for the customer. Hanza’s aim of a single customer not contributing to more than 10% of total sales, enhances Hanza’s leverage.

    – Threat of substitutes. The re-industrialization of Europe has been a near term driver. While this is expected to continue into the midterm, there is no guarantee that the trend towards globalisation continues again – if so for example transport costs come down and geopolitics calm down. The argument here is that cluster manufacturing might be less appealing in an environment without geopolitical tension compared to other ways of managing supply chains.

    – Industry rivalry. As mentioned, manufacturing as a sector Is very competitive. 

    Valuation and forecasts

    The acquisition of BMK and Fortico; provide little customer overlap and arms lenght manufactuering models. For Hanza this means that Hanza has potential to upsell its cluster manufacturing approach to new customers. When Hanzas customers grow, their need for manufactuering increases. Hanza thus grows with its customers, being deeply embedded into their supply chains. Further, with the LYNX program Hanza targets 300 M SEK annual. Defence manufacturing includes drones. . The Reindustrialization of Europe and the European Defence Industry Programme (EDIP) will function as significant tailwinds in the short to midterm. https://commission.europa.eu/topics/defence/future-european-defence_en

    Hanza is trading at a PE 23.6. with 6 billion in sales and a EBITDA margin at 6.3%. Using management guidance: their 2028 plan. Sales at 14 billion and an EBITA margin at atleast 9%. A start 2029 PE stands at around 10.

    Note. Fortico acquisition is all cash and is expected to happen in Q4 2026; with a positive contribution to EPS. BMK is already integrated, and the merger was done issuing new shares. One time costs was materialised in Q2, hinting at a higher 2026 adjusted net income.

    Market share and Competition

    Illustrated above, Hanza is one of the least profitable firms in the peer group. The development though, is best or second best in class. Cicor and Kitron are both attractive alternatives. The lower profitability, can be attributed to recent acquisitions and the implementation. The profitability is expected to improve.

    To Summarize

    Hanza is the fastest growing European manufacturing company, with their aggressive M&A strategy and cluster model. Recent acquisitions fit the overall business model well, expanding in operational capabilities / securities & defence [BMK], customers and scale [Fortico]. Hanza is thus growing both in new product categories and in new customers. The risk is the acquisitions and implementation of these acquisitions and macro economic factors affecting European industry. Current industry trends, favour more resilient supply chains -> which favours Hanza. Hanza is experiencing significant insider buying. The advantage/moat is largely, that the cluster offering is unique and difficult to replicate, which in theory with time should improve margins. The growth comes from industry tailwinds, m&a and the superior positioning.

    – The segment defence & security is going to have a positive contribution to sales and margins.
    – The Fortico acquisition is going to provide potential for up selling to the new customer base.
    – If managements guidance hold, the company is currently undervalued.

    – Broad exposure to European industry. Any draw down in the economy, might affect profitability.
    – Higher interest rates and increased leverage are going to affect m&a strategy in the short term.
    – Inorganic growth is less valuable than organic growth.

    Extra:

  • Analysis Service Now [NOW]

    To summarise [TLDR]

    Service Now operate and lead in segments that are estimated to continuously grow significantly. Their positioning is attractive and management is talented. The company boasts significant moats and competitive advantages. In many ways, the bull thesis is leveraging the Service Now platform and the massive total addressable market in Agentic AI. The current key risk is the integration of recent acquisitions. Price target sits at 27% above current valuation – with Service Now notably trading at a PE 80.

    Analysis

    Service Now [NOW] is a Reddit favourite and commonly proclaimed AI agent winner. 

    Under the leadership of CEO Bill McDermott, ServiceNow boasts a highly regarded, customer-centric management team. McDermott’s prior track record of scaling enterprise software has fostered a strong market position with an impressive 120% net revenue retention. Partly attributed to ServiceNow land and expand model, which implies initial high customer acquisition cost and high lifetime value. Customers stay with ServiceNow and ServiceNow has leverage. Changing the system of action, means shutting down operations, changing workflows and retraining employees. The lifetime value and net retention rate is positively affected by ServiceNow’s cross selling. ServiceNow can cross sell because they have a strong brand equity in which they can leverage the service now brand across several business operations – such as customer service management and operations management. In marketing; they would be classified as a branded house. 

    Rhetorically, McDermott positions ServiceNow as the collapse of the traditional enterprise stack. Note. McDermott comes from a background in sales.

    Service Now Q2: 298M net income consisted of 272M other NON! operating income. Positive adjustments to investments, currency hedges etc. One time effects. The Service Now underlying business barely made a profit in Q2!. Meanwhile the McDermott is bragging of operating at rule of 57 targeting rule of 60. 

    The point is – I would not take the very liked and charismatic CEO at face value. 

    Now’s competitive advantage includes its capabilities/competent customer centric management and its relative positioning to legacy software ecosystems traditionally built for silos and departments. Its MOAT is the stickiness of the ecosystem, the costs of developing software in house and the operational advantages emphasised by the competitive advantages. 

    ServiceNow has a 5 year revenue CAGR at 24.06% and net income CAGR at 71.16%. This can partly be attributed to a net income margin expansion from 3.9% to 13.15%. Now is guiding for accelerating growth. 

    Lately Now has acquired and is implementing Armis [cyber security] among others into their systems, laying the foundation to become the AI control tower. Armis a 7.75 billion usd all cash deal made dec 2025, allows Now to better monetize and act on Agents that functions across and on top of whatever system of record the customer is using. This is great because managers need to trust the AI agents they use to automate their workflows. Note that the Armis acquisition is improving their security operations and that the implementation of Armis made it the fastest growing cyber security firm (out of the 10 biggest), highlighting how Now can scale their organisation.

    When customers trust a brand – they are more likely to use that brand. This is especially true with regard to AI agents. Again, ServiceNow has a massive customer base, which might implement ServiceNow AI agents. 

    The last four quarters Now has spend $9.7 Billion acquiring new companies, significantly above their  2025 net income at 1.75 Billion. Now as of Q2 2026 has 19.15 Billion in liabilities and 31.67 Billion in assets. Assets include 10 billion in goodwill. Excluding goodwill Now trades at an asset/liability ratio of 1.1.

    These massive acquisitions hit the operating income in Q2; driving it down from last quarter from 503M to 162M. 75% of it was driven by higher amortization of intangibles (190 million) and SBC (150 million); more accurately R&D increased about 90M (part of the SBC). Note brackets indicate increase. 

    To emphasise Now’s potential in Agentic AI, Now services an impressive 85% of fortune 500 companies. I won’t dig into total addressable markets, just note the sectors IT service management, cybersecurity and agentic AI are growing significantly.

    With regards to margins and future competitive outlook. I estimate compute costs to continuously decrease. Furthermore, I expect Now to have some leverage against the big llm’s such as OpenAI and Antropic. This is due to 1. Their massive customer base 2. They don’t actually need the fancy models for a lot of their use cases. 3. China’s open source models, pressuring pricing. A headwind is the factum OpenAI and Antropic are unprofitable entities that eventually need to increase prices to become profitable. 

    When the development of Porters Five Forces is favorable, then profitability should increase.  I already estimated Bargaining power of suppliers and Bargaining Power of Buyers: As low. The competitive rivalry is low, not because there isn’t competition but because ServiceNow is dominating. With AI the Threat of New Entrants and Threat of Substitutes are considered more pronounced, but I disagree. Creating a system of action is not cheap and requires years of development and/or marketing. Both costly affairs – especially over time.  

    Applying Porters Five Forces – ServiceNow is likely to improve profitability. Remember, above Porters is a subjective surface level assessment – and that a favorable positioning, doesn’t necessarily translate to a margin increase. 

    Now trades at a premium at an estimated 2026 PE at 80.8, commanding flawless execution. Using the above foundation, I am assuming an approximately fair value of 158 USD . Providing a 27% return from today’s levels. 

    The DCF assumes a 10% discount rate, a 25% revenue CAGR that gradually drops to 10% over 10 years. Exit multiple at PE 25. I assume net income margin gradually grows to 27%, from 11%. Admittedly I believe revenue could expand more due to the value proposition customers might get from agentic ai. Note. In Q2 2026 margins were 4%. I have set 2026 margins at 11%. Cyber security and their existing markets, can command massive profitability. Companies like Adobe and Microsoft operate in 25-35% range, with Salesforce and SAP commanding a profitability on par with Now. 

    In Q2 operating profit dropped about 50%. Gross profit was up slightly, though on a lower margin base. Attributable to higher compute cost. Further, operating expenses increased across the board. The acquisitions [Veza, Moveworks, Mission Control & Armis], the implementation of them (implicit the massive bet on Agentic AI) is the cause. Several complex integrations will affect margins in the mid to short term. These are likely to improve, as the integration progresses and as the company scales. 

    Note: 4. August Armis announced another major milestone as it rapidly surpassed $300 million in annual recurring revenue (ARR), growing from $200m in ARR in less than 12 months. Armis Surpasses $300M ARR as Demand for Exposure Management Security Soars | Armis

    Assuming a 400M ARR at a 7.5 Billion price point – Service Now is paying a “price/ARR” ratio at 18,75 or inverse 5,3%. Not cheap; but assuming they can 3x the business using their existing customer base, drive synergies across portfolio and increase share of wallet then it is starting to look all the more reasonable. In many ways, the bull thesis is leveraging the Service Now platform and the massive total addressable market in Agentic AI. And in many ways, the risk is the integration of businesses into the Service Now platform – and then again; PE 80.

  • Netflix [NFLX] attractive entry?

    Pros
    – Paramount/WBD merger creates a highly leveraged competitor with questionable management.
    – Strong FCF and balance sheet
    – Best in class brand equity
    – Trading below historical norms ( PE ).
    – Continued tailwinds in Emerging/Frontier markets
    – AI lowering production costs
    – Strong management (pioneering talent density).

    Cons
    – Amazon Prime and their massive scale
    – Younger cohorts increasingly gaming and watching UGC content
    – Saturated developed markets
    – Uncertainty regarding product expansion/changes to product mix
    – Removal of KPI’s such as semi annual watch time

    Summary
    Ad tiers to drive increased adoptions in emerging/frontier markets. Clear path for AI to improve margins. Plausible market share gain in short term, as competition must improve balance sheet. Development of AD monetisation infrastructure to decrease margins in short term. Netflix is cheap based on historical averages – by some margin, attributable to removal of KPI’s, changes to monetisation and fears of market saturation. The market is increasingly viewing Netflix as a mature media conglomerate instead of as a hyper growth story. If Netflix can maintain high single digits growth, then the current valuation is attractive.

    notes:

    I think AD tiers was a very deliberate initiative to increase reach to emerging/frontier markets. One could fear this would impact margins, as the subscription base grows outside developed nations (lower arpu). Though, the low incremental costs of each new customer, properly offsets this.

    Netflix is required by law to have 30% local produced content. This creates a moat for new entrants, but levels the playing field with incumbents. Note. Amazon & HBO/Paramount has wide access to local content, due to their ownership of local studios.

    Quality companies typically trade at a premium.
    And PE 20 is that.

    Netflix has over a 10 year period consistently improved margins and grown revenue – while it is not a indicator for future performance, it is certainly pointing towards excellent management. Also the company exhibits quality indicators such as massive FCF, profitability and a solid balance sheet. Thus Netflix command a premium valuation.

    Profitability:

    Gross margin = 49%.
    Net income margin = 24%.

    Return on assets = 15%.

    Liabilities:

    Liabilities/assets = 52%.
    EBITDA/Interest = 18.5

    2026 PE = 20x.
    2026 EV/FCF = 24x.

    Analyst expectations:

    2026 PE = 20.4x
    2027 PE = 19.2x
    2028 PE = 16x

    2026 guidance is 13-14% revenue growth (12% FX neutral) and a operating margin of 31,5%.

    A 10 year DCF; exit multiple 20, revenue growth 10% and operating margin improving 0,25% yoy.
    > 6% discountrate. Fair value 115 USD.
    > 8% discountrate. Fair value 85 USD.
    > 10% discountrate. Fair value 81 USD.

    Netflix is my second biggest investment at around 15% of portfolio.
    Not financial advice. I can have made mistakes. Always do your own due diligence.

  • HUBS down 22% pre market; Low Visibility & Headwinds [Q2]

    Expected user growth 9000-10000; actual user growth 7000. Slow start to August; with increased budget sensitivity = I.e. customers less price inelastic, potentially providing issues in up selling.

    Issues expected to persist remainder of the year. HubSpot is positioning itself towards Agentic AI, as they believe this to be a much bigger and much more attractive market. Issues partly stem from the whole “seat based pricing”, as the growth in Agentic AI is likely to at least cannibalise some of the HubSpot licenses. This creates tremendous risk; as visibility is significantly reduced.

    When numbers disappoint in a low visibility environment, then the valuation gets absolutely punished. Today HUBS is down 22% premarket. Management guided for headwinds for the remainder of the year; among these are increased budget sensitivity. This would explain why net upgrades is under pressure, net retention down 1% and a significantly lower single to double digit growth. When management says “increased budget sensitivity” it is important to note that their pricing has increased significantly in recent years; and that the upmarket initiatives are alienating some of their smb’s.

    In short, the presentation showed that the agentic AI adoption accelerated – especially, with regards to upmarket customers. Credit usage increased, even as pricing was decreased. Currently, Hubspot has been temporary hit by offering trials in AI agents. This action is expected to accelerate agentic AI adoption, as customers become more confident in their use cases.

    I am quoting Yamini from memory – “customers dont want 10 different agents from 10 different vendors – they dont want them crawling everywhere”. HubSpot (as well as Service Now, Salesforce, Sap etc) are in an attractive positioning, to automate workflows and improve efficiency for their customers – potentially, entering a immature and absolutely massive market.

    Not financial advice. I can have made mistakes.
    I have shares in HubSpot (and Service Now). Always do your own research.

    Webcast: https://hubspot-q2-2026-earnings-call.open-exchange.net/webcast
    10Q: https://ir.hubspot.com/node/15681/html

    There is no doubt AI agents is going to cannibalise subscriptions. BUT!. Why would that destroy bottom line? In Q2 revenue grew 20%, but operating expenses only grew 6%. We are currently not seeing a wipeout of margins – quite the contrary. The market (me) is uncertain about whom is winning agentic ai and the powerdynamics in play – if Hubspot and all the other crm platforms are just using OpenAI and Antropic, it might hurt their profitability due to little leverage. Furthermore, Hubspot might be incentiviced to provide cheap solutions, to accelerate adoption. In short, Hubspot is acting like this is going to be a megatrend – where the companies survival absolutely depends on leveraging this trend – if they fail, they might be gone for good (or we will be diluted to oblivion). Point is – I am not sure agentic AI is going to crush the bottom line, I am unsure how agentic ai is going to affect Hubspots competetive positioning. The valueproposition agentic ai gives the customers (automation of officework) is abselutely massive, and points toward pricing power -> increased profitability. Applying a expected value framework, then the value is heavily affected by the risk of disruption.

    Microsoft and Amazon are developing agents.
    Smaller startups are developing agents.
    OpenAI and Antropic are developing agents.
    SAP, Salesforce and ServiceNow are developing agents.
    Most of the peer group (smaller crm platforms) are developing agents.

    TLDR: HubSpot is preemptively sacrificing potential short-term monetization and accepting gross margin compression to ensure they remain the system of record. Under an expected value framework, the massive value proposition of automating office work is heavily discounted by the reality that HubSpot does not control the foundational AI layer and must compete in a highly saturated, commoditizing market.

    I am unsure about the strategic direction – therefor I am selling.

    Not financial advice. I can have made mistakes.
    I have shares in HubSpot (and Service Now). Always do your own research.

  • Tesco is a sell

    The Bull thesis

    By leveraging its extensive consumer data, Tesco can launch products that have superior market fit. Increasing white-label product sales are going to have a positive impact on margins. Tesco simply have the leverage and data advantage, to take this market share away from exciting food and beverage brands.

    Furthermore, Tesco can efficiently scale their product mix, by leveraging the Tesco brand into mobile services, insurances and ecommerce.

    Tesco has a ton of prime locations, that new entrants would have to compete directly with if they want to take market share and grow in UK. Furthermore, they have economics of scale to leverage stronger deals with suppliers and decrease overall costs.

    To sum: Tesco has strived to improve their brand equity, and this is reflected in their market share development. All the while, the Tesco brand can be leveraged across services.

    The Bear thesis

    Tesco has previously failed entering USA and ASIA. This makes the case for a limited runway – market growth strategies, might not be for Tesco. Tesco is highly exposed to the UK consumer, and growth is limited to increasing share of wallet. Market penetration strategies have simply not been feasible. Especially with Tesco’s local appeal. Competition from Aldi and Lidl is likely to affect margins and earnings growth for the foreseeable future. White Tesco is considered a consumer stable, and they are – earnings are likely to be slightly affected by volatility in consumer purchasing power in the UK and input costs. Furthermore, the British pound has underperformed the EUR and USD for a while now and might have a material impact for the foreign investor.

    While the bull case for Tesco heavily emphasizes margin expansion, the UK governments are heavily opposed to increased food pricing, possibly creating a regulatory risk if grocery stores become too profitable. Tesco’s brand is not strong enough, as consumers simply don’t care if they shop at Aldi, Lidl or Tesco. They are picking the cheapest and most convenient grocery store. Finally, A 5–10-year corporate bond provides a yield similar to Tesco’s at current valuations.

    To sum: Competition is fierce, market penetration growth is limited and risks pertain.

    Conclusion

    I believe Tesco is going to increase its margins, through white labels and improved brand equity – but their market share is most likely to stay flat in the short to midterm. I assess Tesco to be fairly valued, trading at a premium to other retailers. This is not unreasonable since they are and have the potential to expand product categories in both vertical and horizontal integration.

    They have a brand that Is deeply embedded in UK culture and that people increasingly trust (partly attributed to past setbacks). Issue comes with brand dilution, people don’t trust cell phone providers and especially not insurance companies. This will increase distrust in Tesco, hurting their brand equity.

    In all fairness, investing in grocery stores drives similarities to investing in car makers or airlines. Massive competition drives uncertainty about future growth and compressed margins.

    Tesco at a pe above historical averages, above industry averages in a risky macroeconomic/regulatory environment does not condone investing.

    I appoint a sell rating, as Tesco fair value is PE 13. 23% below current PE. Note: Tesco might be able to leverage their brand across segments, gain market share etc. but based on their marketing strategy this is too questionable. There are even better investment opportunities in today’s hyped markets. Consumer staples as a sector have underperformed, and rightfully so – they were way too expensive! But they are still not value.

    About Tesco

    Tesco is Tesco, Tesco Mobile (UK’s biggest mobile network operator), Tesco insurance & money services, One Stop, Booker (UK’s leading food and drink wholesaler) & Dunhumby (A global leader in customer data science).

    Tesco is in five markets, with UK being the most significant market (in terms of size). Tesco is the leading grocery retailer in UK with 28% of the market share and 4500 stores. Tesco also has 180 stores in Ireland, 180 in Czech Republic, 180 in Slovakia and 200 in Hungary.

    The Tesco Brand (grocery stores)

    Tesco Grocery Stores (CBBE):

    Tesco brand salience (awareness & recognition)

    Tesco, with their long history and massive presence in the physical environment in UK drives high awareness and recognition. Most consumers in UK, have at some point evaluated their opinion on Tesco for better or worse. This creates strong brand nodes, which makes consumers able to quickly know exactly what the Tesco symbol symbolizes (depth). The frequency of how often these brand nodes are recalled is highly dependent on the physical environment (width).

    Brand Image (identity mix)

    Tesco’s supermarkets are generic supermarkets. They don’t particularly appeal to the seven senses. They are brutalist like architecture with bad smells. They are not made to be pleasant experiences. They are created to be convenient and offer large selections of groceries. Tesco’s stores are massive, offering a wide range of products.

    Tesco is a low-price mass retailer, and prices its products as so. With some premium products. Tesco’s white label brand (Tesco Finest) is not an exception, these are meant to be premium products.

    Tesco’s employees are wearing generic ( ugly ) uniforms. The logo has not been updated since inception, and is a rigid red text stating Tesco. This is visible on the front, on the employees and on the shopping bags.

    Tesco’s promotions are personalized offerings with email/app notifications and tv advertisements. Tv advertisements are good at reaching an older audience and create awareness (top funnel). App/email notifications are good for driving loyalty (bottom funnel).

    Brand Performance

    The primary characteristic of Tesco is the accessibility of food. This is a point of parity with other grocery retailers.

    Secondary features of Tesco are massive breath of products (note – the grocery store). This is a point of difference from other grocery retailers. Further, Tesco is offering bundled products such as mobile and insurance. That Aldi and Lidl does not.

    Brand Judgements & Brand Feelings

    Brand judgements is the quality, brand credibility & brand consideration.

    Brand feelings is:

    1. What feelings does the brand elicit in consumers’ hearts?
    2. How does the brand make consumers feel about themselves and their relationship with other people?

    Tesco’s products are a direct reflection of the brands they are selling. Because the product is from Tesco, does not mean it is high quality. This is why food brands are still relevant today; they are something consumers use to identify products and themselves. Tesco’s finest are quality products at a premium price (masstige).

    When shopping at Tesco the supposed emotional reactions are the ones of being safe, comfortable and reassured. People want good quality and good price. They want to be reassured they are not cheated or getting sick. Shopping in a supermarket for most is not supposed to be an exciting and/or fun experience. Some might pick supermarkets on the basis on social approval and/or feeling pride. This is not the case with Tesco.

    Tesco’s brand credibility has suffered under past scandals, that older demographics (millennials and up) will still remember. Horsemeat in meat products, created distrust to the Tesco products and supply chain. Customers were saying – they don’t even know what they are selling. This lack of credibility makes the customer feel distrust and to an extent hatred towards the brand. How can you know what you are buying is, if the one who is selling it doesn’t even know. This shakes the consumers, as the bottom of the Maslow pyramid is hurt. Another scandal was financial fraud (inflating earnings). This made consumers think it was led by unethical profit first management, hinting at a deeply rotten organization with a toxic culture. Deeply hurting the brand equity and perceived positioning as a local brand (these are supposed to be credible and hold high ethics).  Anyhow, these things happened a long time ago but will still reflect the older demographics’ perception. Tesco is no longer the local grocery store; they are a multi-national corporation. Tesco has managed to improve their brand equity; this is reflected in their existence today. There simply would not be a Tesco without trust and credibility. Consumers who have been going to Tesco for years, feel safe going to Tesco – they know what they are going to get and they know they will not get sick. It is the same old. Tesco’s increase in market share can partly be attributed to their improved brand equity.

    When consumers consider where to shop, they consider first and foremost convenience (i.e. distance), the prices and the product mix. These considerations might change with consumer trends (i.e. purchasing power). Tesco’s club cards are a massive driver of consideration – especially for users in the paid tier.

    Brand Resonance

    Tesco’s relationship with their customers is most likely an interdependence relationship. Tesco is dependent on its customers and the customers er dependent on Tesco. In these relationships are more frequent and diversified and endure over time. Even when there is low affective involvement.

    Where in Tesco’s is placed in the four categories of brand resonance is difficult to assess and highly polarized. Being a retailer consumers will typically pick the one that is most convenient. This leads me to assess them as behavioral loyalty; consumers use Tesco simply because it is the one that is most convenient for them. But this doesn’t illustrate fluctuations in market share and loyalty cards. In fact, I will argue that an increasing number of consumers have a preference. They have their favorite products, and they know where things are. This moves them up in the brand resonance chain – some more than others.

    Tesco omni-channel marketing

    Tesco drives omni-channel marketing through their app. Data works as a competitive advantage. Tesco can leverage data points from a single consumer, partly because when consumers buy products in Tesco using their loyalty cards, they create a data point. The loyalty cards further let Tesco keep track and offer personalized discounts using AI. On top of this, data helps Tesco know what products are popular and which aren’t. This helps Tesco select products with a strong product market fit. They simply know what consumers want, before any brand they are selling knows – and this is likely to continue driving market share in their Tesco Finest segment.

    Tesco Positioning Strategy

    Tesco has over the years expanded into different services, using their Tesco brand (a Monolithic Brand). An approach that can drive high adoption rates, with little advertisement expenditure. The downside is that any harm to the Tesco brand will damage Tesco across its services. This brand architecture allows for the optionality of launching new services, for the investor an important growth driver. The key issue is that, the distrust the average consumer has in financial services might spill over to Tesco.

    Tesco’s positioning is using a local positioning strategy. They are appealing to the heritage, nostalgia and the mass. In its DNA, it is a worker’s brand. This is a strong positioning in UK’s proud “Glasgow” culture – creating mass appeal. This is emphasized by their latest support of British farmers and communities. This comes to expression through the identity mix, which I addressed before.

    The Tesco Community (Architecture of Affiliation Framework).

    Building a strong brand community is not only a marketing strategy, but also a business strategy that must be implemented across the organization. Brand communities drive increased loyalty. Note loyalty has been proven to follow market share, as is the case with the law of double jeopardy and the duplication of purchase law.

    Communities are not built around the brand; the brand should be built around the community. This requires a customer centric approach; something Tesco is implementing across all its businesses. Tesco is engaging with and in the community through partnerships with its community – the everyday working joe – through addressing key societal issues such as regulatory pressure on farmers, parental leave and healthy food for kids.  

    “At Tesco, we are campaigning not only on behalf of all our colleagues but for people and communities across the country. Our view is that reforms are long overdue. Paternity pay in the UK is the lowest in Europe and paternity leave is out of step with how most couples want to share their parenting responsibilities” How Tesco is backing working families

    “Our farmers told us data collection, innovation, financial sustainability and collaboration are all areas where we can help, and so that’s where we continue to provide assistance.

    Whether that’s testing and scaling innovation on our low carbon concept farms, providing financial support for farmers to achieve shared sustainability goals, or calling on the government to help establish a standardised framework for environmental data, we want to play our part in supporting our farmers and the wider sector” Partnering with our British farmers

    “We see the pressure families are under, particularly when budgets are tight and healthy food can start to feel like a stretch rather than a given. As a supermarket, affordability matters, but price alone does not solve the problem. What really makes the difference is everyday access, real, practical opportunities for children to eat fruit and vegetables as part of their normal routine” Free Fruit and Veg for Schools: Our Big Ambition to Reach One Million Children .

    Finally, brand communities should not be tightly managed. They belong to the community, and excessive corporate control destroys them. As illustrated with above citations, Tesco is not fighting the community, it is supporting the community/local culture through initiatives.

    While it might sound superficial, the people who engage in these activities are the community. It creates a tribe through connections.

    Tesco helps build its community through hubs (celebrity endorsements). This is for example the case with Jamie Oliver advertising Tesco Finest. Tesco is closest to a pool affiliation. Tesco’s customers are united by a common goal of cheap and convenient grocery shopping. This type of affiliation is highly scalable because it does not rely on relationships; it can simply be advertised. Pool affiliation is the weakest form because cheap shopping is not uniquely a Tesco thing; it is highly prone to competition from Aldi and Lidl.

    Valuation & Ratios

    Grocery chains usually trade at a pe around 10-15. Tesco is trading at PE 16.

    Tesco’s profitability is very low. With a consistent operating income of around 4-5%. And a net income around 1-2%. These are industry standard, but nonetheless they are unappealing.

    Note: Retail is 87% of their operating income.

    Tesco now

    As Aldi is being perceived as cheaper and running without same loyalty/omni channel features positions them strongly to directly capture Tesco’s local (workers class) appeal. Tesco recognizes this and specifically advertises using a price match on Aldi’s products. Simultaneously, is Tesco targeting (those premium brands) with (their others stores and Tesco Finest). Tesco is currently experiencing regulatory headwinds with considerations of capping food prices on necessities – which to me seem unlikely, as grocery stores are already operating on a low margin. Tesco is seeing growth in its insurance segment.

    Disclaimer

    Note: this analysis mainly addresses Tesco from a marketing management and strategy point of view. It is by now means an exhaustive analysis of all possible elements – for example it does not address economics of scale, competitive dynamics (porters five forces) or the macroeconomic and regulatory environment facing the company. Neither does it address the whole sale business or telecoms business etc. Investing requires a holistic approach, which accounts for all possible elements, to structure a genuine insight into the company’s current and future prospects for creating shareholder value. Future analysis must address the insurance business, as this is a particularly important aspect of the bull thesis (leveraging the brand). While the insurance business is still small comparatively, it has grown immensely over the last two years. Another important element that could and should be addressed is the vertical integration of, for example, the whole sale business and increasingly farming.

    Competitive advantage

    Tesco’s biggest moats are not brand equity and consumer loyalty. It is a geographical moat and economics of scale. The geographical moat is the placement of supermarkets, that new entrants will have a hard time competing with. They must either locate in a worse location or next to Tesco and/or another retailer. With the grocery store already running at low margins, this is expensive and thus unlikely to be executed. The economics of scale is leveraging deals with branded goods and cost advantages. Not a very strong moat, in a market with many big players.

  • SharkNinja a marketing powerhouse

    SharkNinja a marketing powerhouse

    Introduction

    SharkNinja isnot a generic hardware manufacturer – they are an innovative and disruptive organization; build to leverage consumer insights and agile production with an entrepreneurial mindset and omni-channel marketing competencies. Their success has been emphasized by a 21% CAGR since 2008 (Q1 Investor Presentation, 2026).

    As a marketing student and avid investment analyst, it is hard not to get excited.

    About sharkninja

    SharkNinja is a US firm specializing in small household appliances, currently expanding internationally – with an 32% international sales growth and 8% domestic sales growth YOY. With domestic accounting for 65% of sales.

    According to Circana Ninja is America’s #1 blending and processing kitchen system brand and Shark is the #1 vacuum brand in the United States in dollar sales (Annual Report, 2025). Lately the Shark brand has been expanding into Beauty and Home Environment Appliances; with a YOY growth at 41%, illustrated underneath.

    (Q1 Financial Statements, 2026)

    Most of SharkNinja’s competition is operating at a lower price point, with exceptions such as De’Longi, Dyson and Vitamix. SharkNinja’s products are priced in the mid-range segment (Annual Report, 2025).

    Furthermore, SharkNinja’s organization is characterized by an entrepreneurial and fast-paced culture (Ibid.,).

    SharkNinja does not own their own factories but is using third party partnerships (mostly in China), but spread out throughout Asia (Ibid.,). Their production is agile and allows for incorporating insights and adaption, in any stage of production (according to SharkNinja) (Ibid.,). This means that SharkNinja can mitigate some tariff risk.

    Sharkninjas marketing strategy

    SharkNinja is two brands that leverage a wide range of products – this makes them a branded house (though, arguably it is two branded houses – a house of brands). Anyways, this business model has inherent flaws and strengths. Most commonly addressed is the fragility of having just 1 brand – any, shitstorm or unfavorable development in brand equity, would drastically affect the future prospects of SharkNinja. Another key issue is the heterogeneity of customers across demographics, interests and geographies – a single brand, simply cannot address all and everyone. On another note, the advantages are equally exciting – market share is surprisingly negatively correlated with amount of brands (less brands -> more market share). This might be attributed to the massive efficiency gains from marketing a single brand across several products and markets. In short, SharkNinjas brand architecture is theoretically highly efficient. Further, a branded house creates cross selling, when a customer buys a NinjaCREMi they are more likely to also buy a Ninja coffee maker.

    On another note, the number of brands is negligible, if the brands don’t resonate with the customers. Using a customer centric model significantly reduces potential mismatch between customer perceptions and brand/product attributes.

    SharkNinja is using a surrogate positioning strategy. This is the positioning strategy that historically has yielded the biggest returns. The customers are not buying the brand because of its features or functional benefits. They are buying it because it reflects them (obviously some are buying it because of the features and their perceived value in terms of quality and price). But broadly speaking, brands are expressive tools. SharkNinja’s products are made to be shared and engaged with, and thus it is not random they are selling pink blenders and espresso machines – these cater to a specific “pretty, trendy influencer audience”. I will argue that this is the customer group that adopted SharkNinja’s brand and made it their own. With time, different subcultures will engage with the brand – and the perception might change completely. These are the new rules of the game. I am further addressing this under digital marketing strategy.

    Sharkninjas omni-channel marketing

    OC requires data flows between channels, and a cohesive customer experience across offline and online channels. These are not easily replaceable – and in many cases, involves extensive hiring processes to ensure the right talent and reorganization to ensure data is shared and leveraged across channels. It is not a “new” approach and is used widely – but to the extent SharkNinja leverages this approach and has made it part of their DNA makes the case for NinjaShark’s omni-channel marketing competencies – a competitive advantage unlikely to be disrupted any time soon. This is because omni-channel marketing is an organizational structure that must be implemented in everything the company does.

    digital marketing

    Online channels is arguably NinjaShark’s biggest competitive advantage.

    SharkNinjas followers increased 120% in 2025 – far outpacing competitors who grew 8% on average with a much smaller userbase (Annual report, 2025). This significantly drives awareness (eWOM) and brings several other significant advantages. When a customer likes a brand, it is a direct acknowledgement of said brand – it emphasizes customer loyalty and brand resonance. It functions as low CAC and increased return on advertisement expenditures.

    Above picture is screenshotted today’s date: 20-05-2016 from SharkNinja.com. It emphasizes how SharkNinja’s brand ambassadors are sharing and interacting with their brands. This drives significant eWOM and customer insights. A strong presence on social media will undoubtedly drive significant awareness and recognition.

    Brand ambassadors are satisfied customers and influencers advocating for the brand through offline and online channels. This is exceptionally important and risky approach to digital marketing. Two things need to be addressed, to properly understand SharkNinjas business model, 1) In postmodern marketing storytelling is a driving force and 2) influencers and brand dilution.

    1. In postmodern marketing, the brands have lost control over their brands. All they can do is lay out the pieces in the massive stadium of consumers interaction. SharkNinja is doing a terrific job here.

    For example, Ninja, their kitchenware is highly Instagram-able “toys”. This creates a native incentive to share their recipes and cooking – to their highly engaged subcultures. Furthermore, Ninja creates urgency and scarcity by dropping limited edition products and limited stock. This creates exclusivity and thus fosters the trend -> the trendy consumer. Ninja also runs an “always on” marketing strategy, that makes them able to engage with their communities and address issues that will come up, when consumers are “hijacking” the story telling – for example by complaining about a product that arrived broken or incomplete. Competitors are simply not operating with the same online presence as SharkNinja and they are simply not operating with the same capabilities in forming the narrative – an increasingly important dynamic, if a brand is to sustain their equity.  

    • Influencers (as well as brand ambassadors) are inherently their own brands. Interacting and engaging with these will cause spillover effects. Again, SharkNinja’s brand is heavily influenced by the people that engage with it and how they engage with it. It is central that the influencers in question are both passionate and transparent about the products they are presenting. Anything else would negatively impact credibility. Imo transparency is still a grey zone but the subcultures these influencers engage in are highly passionate subcultures such as lifehacks and cooking. Essentially, SharkNinja drives significant momentum through influencer marketing with incredibly low customer acquisition costs.

    In near term SharkNinja is focused on rolling out TikTok sales channels and improving their own webpage. The latter is expected to slightly improve margins.

    SharkNinja’s success is highly dependent on their social media strategy, remains successful, and for the investor, should be monitored accordingly.

    offline channels

    SharkNinja’s use of third-party sellers, reduces their optionality for upselling, creating a “mixed senses” experience – and leaves power to the retailers. Though a strong brand equity drives leverage in negotiations – which is necessary: in the context of retailers increasingly capturing more of the customers share of wallet.

    Furthermore, not owning own offline sales channels removes high fixed costs and increases scalability.

    translating marketing strategy into shareholder returns

    A strong marketing strategy creates brand equity, which translates into shareholder value. Lower cost of acquisition, increased customer lifetime value through repeat purchases and stronger pricing power.

    The previous analytical points create the narrative that SharkNinja’s expansion strategy is likely to continue at high growth rates especially due to a successful online marketing strategy. Slight margin expansions are expected because of the synergies between TikTok marketing and their existing appeal to subcultures – furthermore online direct to consumer sales channels are also expected to have a positive effect on margins.

    Established market growth is expected to continue at a lower, but still high single digits due to the proven ability to disrupt product categories and marketing efforts.

    The establishment in new markets and new products creates an appealing growth story. Though, It is still unclear how SharkNinja would resonate in markets outside USA, Europe and Latin America – but at current stage, there is no doubt about the scalability of the business. This commands a premium, to other small kitchen appliances, such as De’Longi and Vitamix.

    Note

    This analysis is not addressing the macroeconomic environment –> which, can have material effects on SharkNinja’s performance. Especially regarding customer purchasing power.

    Will new product categories perform equally well? Ninjas have grown massively on the air fryer and Shark on their Dyson-like vacuum cleaner. Can SharkNinja keep renewing themselves and entry/disrupt product categories? SharkNinja is leveraging trends to the max. But will they be on top of the next trends? Can SharkNinja continue to stay on top of the narrative surrounding their brand?

    valuation and financials

    SharkNinja is an incredibly profitable and asset light business with low debt, as illustrated underneath:

    Gross profit/Revenue 53%,
    EBITDA/Revenue 15%,
    EBIT/Revenue 14,5%,
    Income/Revenue: 11%

    Income/Assets: 13%

    Income/Liabilities 26%,
    Asset/Liabilities 200%

    SharkNinja trades at an EV/EBITDA: 14x and at a PE 22.7x. (24-05-2026). Expensive relative to competition but neglectable if assuming a low double-digit growth; about 15%. Assuming a stable macroeconomic environment, this analysis sets a buy rating and a target price at around PE 30 or 148 USD. This indicates a potential of 32%.

    SharkNinja is a marketing and innovation house with a runway for continued high earnings growth, this is why the target price is at an PE 30.

  • Match Group’s New Leadership: A Turnaround for the Dating Conglomerate

    Match Group’s New Leadership: A Turnaround for the Dating Conglomerate

    Ticker: MTCH. Not financial advice.

    Introduction & management

    Match Group “recently” changed their CEO (among other leadership changes), and as he stated during the Q2 earnings call: “Tinder needs a lot of work. It has grown stale because of short term monetization & lack of innovation.” Additionally, there is a general slowdown in the online dating market.

    profitability

    On the other hand, Match Group has a reasonably profitable business, with an net income / non-current assets ratio of 19% and an net income / revenue ratio of 18%. Furthermore, the new CEO has been making the company more agile, partly by laying off 20% of managers and reducing team sizes; and furthermore by increasing focus on product development. Established dating companies like Tinder benefit from strong network effects.

    balance sheet & capital allocation

    Match Group has negative equity, and half of their assets consist of goodwill. Their MAU (Monthly Active Users) has been declining since 2022. Furthermore, Match Group acquired HyperConnect in 2021 at what appears to be an overly optimistic price, leading to massive write-downs.

    But even with Match Group’s negative equity and high proportion of goodwill, they are executing significant share buybacks. This can be explained by a low interest compared to earnings yield 6,5%. This indicates a shareholder-friendly and aggressive capital allocation strategy that also suggests management believes the company is attractively priced (or he is signalling to the shareholders -> no more expensive acquisitions!).

    Note: Match Group has a net income / (liabilities + goodwill) ratio of 8,7%.

    market

    User sentiment across the industry is historically poor, driven by a perception that dating apps profit from keeping users single. The new CEO has signaled a strategic shift toward brand health, stating, “I would take a positive word of mouth over a $15 subscription any day.” This marks a essential pivot from short-term extraction to long-term value.

    Note: Match Group’s declining MAU stems from the Evergreen segment and Tinder, whereas Hinge is experiencing impressive growth.

    Conclusion

    In my opinion the “new” ceo, seems to be doing the right things. The stock is priced for stagnation – and in my optic – that might just be a tad too pessimistic – even with a historic horrible capital allocation and a trash balance sheet.

    Disclaimer

    Not financial advice – always do your own due diligence.
    I can have made mistakes. I have shares in Match Group.

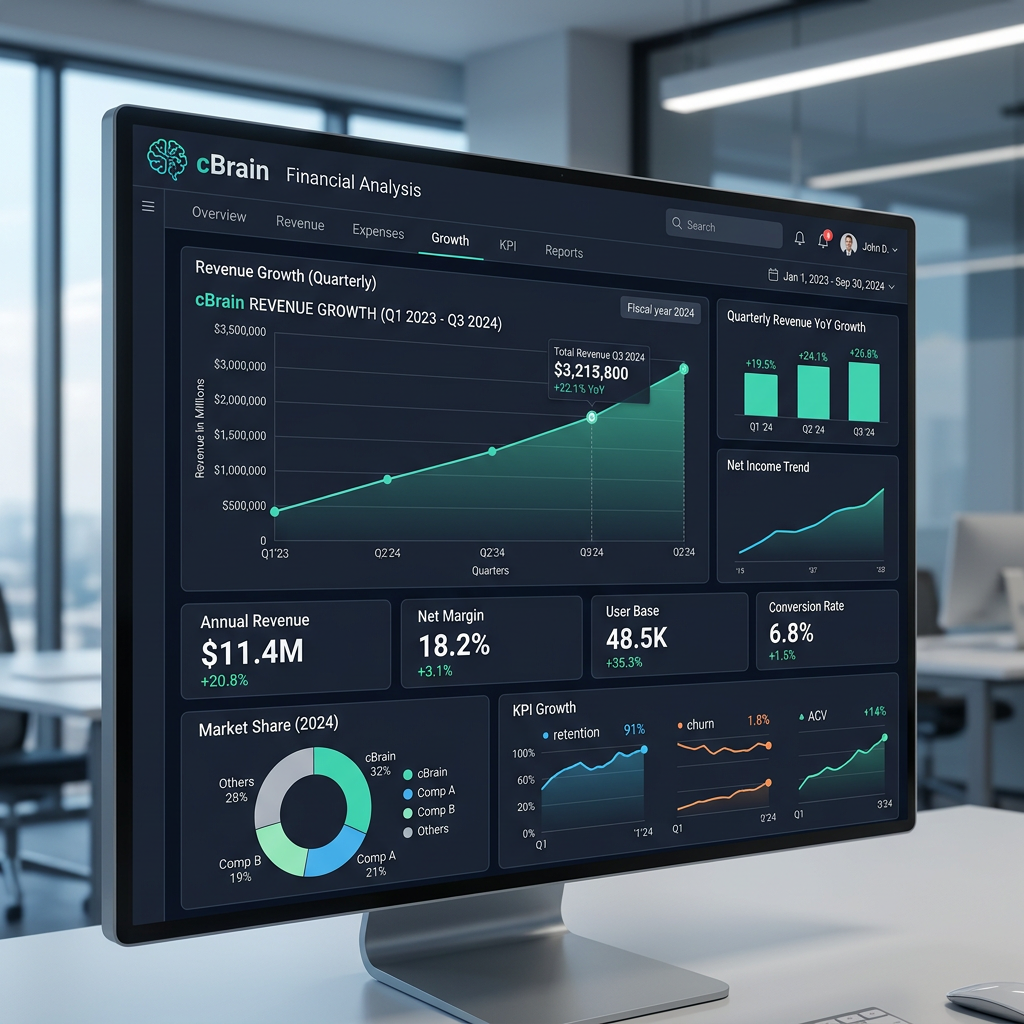
  • Assessing cBrain’s Potential in a Competitive Government Software Market

    Assessing cBrain’s Potential in a Competitive Government Software Market

    Everyone can code now – but not everyone has brand reputation, customer relations or the competencies to navigate the bureaucracy – all these key elements might be overlooked and misunderstood at the current valuation.

    cBrain claims to have a total addressable market of 325 billion DKK in the global government software market.

    But; How much of this market is cBrain likely to capture?

    #1 Competitors

    cBrain is not entering empty territory. In the US, UK, or Germany, local equivalents of EG and Systematic already possess the exact same bureaucratic and relational moats that cBrain enjoys in Denmark. In a low churn sector, does this severely impact TAM.

    #2 New Entrants

    If AI allows any localized startup to build bespoke workflow tools rapidly, the frequency of new entrants is mathematically high. However, the consequence of this threat to cBrain is remarkably low. Central governments do not buy critical infrastructure from startups. They demand ISO certifications, heavily audited sovereign cloud compliance, and a decade of referenced reliability. This bureaucracy acts as a moat against disruptive new entrants.

    #3 Need for product development

    cBrain’s products are essentially:

    – F2 paperless – A highly disciplined, standardized digital filing cabinet and routing system

    – F2 climate – The exact same F2 Core engine, but pre configured to process carbon permits, ESG reporting, and green subsidies

    – F2 customization – ServiceBuilder is the low-code toolkit that allows local consulting firms to configure F2 for local governments.

    These products are by no means representative of the whole 325 billion DKK TAM. For cBrain to ever approach this figure, it would require excessive product development into areas outside their core competencies. Because F2 does not replace ERP systems or heavy infrastructure, a more realistic TAM is closer to 10% of their reported figure. To extend beyond this 10%, cBrain cannot rely on a simple copy-paste of their current product into new markets; they would need extensive R&D and a fundamentally different sales reach.

    So; How are cBrain planning to capture this market?

    #1 With aggressive sales in new markets through external companies.

    cBrain is pivoting hard to an “F2-for-Partners” model, where external consultancies can install and implement cBrains F2 products. They are building tools (F2 ServiceBuilder) that allow external stakeholders to configure and implement the software.

    While this should propel potential customers – it might also be a double-edged sword – Giving sales channels to external partners unavoidably gives away control of own sales channels and execution, potentially damaging cBrain’s reputation and customer relations.

    Can cBrain copy paste its Danish government competencies to other governments?

    Most likely no. Expecting a 1:1 frictionless interaction using “the Danish way” in different cultures with different “ways of doing it” – will undoubtedly provide friction across stakeholders. With that said – cBrain already has customers globally; proving their model can be exported.

    The Corporate Sustainability Reporting Directive (CSRD) and the Corporate Sustainability Due Diligence Directive (CSDDD) are currently being implemented. This is an opportunity for cBrain as their F2 climate can give them “a foot in the door”.

    Also, what about incentives and management?

    Per Tejs Knudsen founded cBrain in 2002, took it public in 2006, and remains CEO of cBrain — that’s over 20 years of continuous founder leadership. He holds shares through his personal holding company, Putega Holding ApS. CTO Thomas Qvist is also a co-owner through Felida Holding ApS and has been with the company since 2003. The two co-founders did sell a combined 4.2% stake in 2021 to bring in institutional investors. Per received total annual compensation of roughly 3.2 million DKK as of 2024, with base salary of about 2.2 million making up the majority. For a company with a market cap around 3 billion DKK, that’s remarkably modest.

    This highlights a long-tenured management – with high insider ownership – resulting in high alignment with shareholders. Finally, the board is diverse and consists of expertise within government, IT and law.

    Also, Per Tejs Knudsen has a Master of Science in Engineering from the Technical University of Denmark (DTU) and HD in Accounting from the Copenhagen Business School.

    So is cBrain a good investment?

    Assuming cBrain can capture 20% of my revised TAM. At a 20% income ratio. Are we looking at a 30 times increase in earnings.

    Math stuff

    Revised TAM (product-relevant market):
    10% of 325B = 32.5B DKK
    Addressable share (realistic market capture):
    20% of 32.5B = 6.5B DKK
    Potential income at 20% margin:
    20% of 6.5B = 1.3B DKK
    Earnings multiple: 1.3B / 43M ≈ 30x current earnings

    cBrain currently (date: 05.04.2026) trades at a TTM PE of 30.

    The hurdle of international expansion is massive. Competing with existing national players is not an easy task – But CSRD and CSDDD regulation might boost adoption of the F2 platform. Another potential boost to sales and market share is the adoption of third party consultants. With external partners the scalability significantly increases – at the cost of customer relationship management. Though the incorporation of external partners partly resolves the issue of difference between cultures and workflows – by allowing for customization.

    A PE in the 30s demands strong execution! And headroom for growth. cBrain has both. But can they capitalise and scale in new markets? A patient investor might wait and see – I assume the current skepticism surrounding software companies is overdone – and am willing to take on that risk. This is not a margin of safety play – but an expected value play (asymmetric risk reward).

    Scenario analysis

    Scenario weight 10% = 30 times increase in earnings; exit multiple PE 25. Potential market cap = 32,250M DKK

    Scenario weight 65% = 2 times increase in earnings; exit multiple PE 20. Potential market cap = 1,720M DKK

    Scenario weight 25% = no increase in earnings; exit multiple PE 15. Potential market cap = 645M DKK

    Current market cap = 1,290M DKK

    Weighted annual return = 4,504 / 1,290 = 3.5x or 13% a year – over a 10 year horizon; assuming no discount rate. This is under my normal margin of safety at 20% – with a large upside pulling up the average return, meaning great risk of failure. So why am I still considering investing? It’s plus EV and I trust the management. But, In this case; for a 30PE company, there are simply too many IF’s. The uncertainty regarding the product and competition – makes this bull thesis too fragile. I am looking for high conviction, high growth and conservative pricing. cBrain as an investment thesis, is simply not there yet.

    Notes & Key Issues

    Two conflicting statements from cBrain annual report:

    Note : “cBrain estimates the global addressable market for the F2 digital platform to exceed 50 billion USD” (page 14, cBrain annual report 2025).

    Market analysts estimate the global government software market to exceed USD 50 billion, driven by continued digitalization at national, regional, and local government levels” (page 6, cBrain annual report 2025).

    Based on my analysis – these two statements are contradicting. I have left it for now. TAM are notoriously difficult to assess. For this analysis to truly shine it really needs two things:
    1. Using cBrains TAM assessment is questionable – as I truly don’t know what they estimate as “global government software market. A homemade TAM would significantly improve this analysis.
    2. I would need to know more about the product and how satisfied customers are with it.

    Another thing –

    Financial Overview (DKK millions)

    Financial20222023202420252026E
    Revenue188239268251275–290
    Revenue growth+27%+12%-6%10-15%
    EBT4981865641-58
    EBT margin26%34%32%22%15-20%
    Net income (approx)38636543

    Revenue fell 6% and margins compressed from 32% to 22%. cBrain attributes this to delays in large government projects, and they’re guiding for a recovery in 2026. Short term profitability is being sacrificed for increased revenue growth.

    https://www.cbrain.com/post/cbrain-announces-next-phase-growth-plan-and-short-term-financial-targets-for-2026

    Debt:
    Liabilities/Assets=18%
    Income/Liabilities=61%

    Profitability:
    Income/Revenue=17%
    Income/Assets=11%

    This is a very profitable company – with very low debt. Meaning shareholder dilution is unlikely to fuel growth.

    What do analyst expect?

    2025202620272028
    PE52.1x24.2x15.9x11.8x

    Note 2026 PE is a tad lower than what cBrain themselves guide!. As cBrain is guiding for a real possibility of declining income. These analyst estimates are likely overly optimistic. Market expansion is expensive.

    Gemini 3.0 and Claude 4.6 has been used to improve readability.

  • Trifork’s Pivot: Navigating Tech Disruption and Future Growth

    Trifork’s Pivot: Navigating Tech Disruption and Future Growth

    Note: Not financial advice. I have shares in Trifork AG.

    Macro headwinds

    Trifork is facing massive structural headwinds. Tech layoffs have flooded the market with programmers, and AI now lets anyone produce good enough code – lowering barriers to entry, increasing competition, and compressing margins across the consultancy sector. Vibe coding further commoditizes “easy to make” applications. However, this risk doesn’t fully apply to “must absolutely function” sectors like security, aviation and healthcare.

    The pivot challenge

    The unpredictable nature of a sector in disruption is the biggest risk for Trifork. The second biggest is the pivot from selling hours to products.

    This pivot is fundamentally harder than it looks. Trifork’s organisational DNA is agile consultancy – scrum teams, sprints, client-driven backlogs. A product-first organisation is a completely different animal. It demands roadmap discipline, saying no to custom requests, investing heavily before a single customer pays, and building sales and marketing functions that consultancies typically don’t have. Being agile does not make you a product company – it makes you good at iterating quickly, which is necessary but not sufficient. The question is whether Trifork can rewire its culture and incentives from “deliver what the client asks this sprint” to “build what the market needs this year.”

    The success of Trifork’s future earnings is highly dependent on their ability to make this change – it is still unclear whether Trifork has the competencies needed.

    A few questions remain unanswered – Can Trifork sell big software solutions? Will potential customers pay? And how much?

    2025 Annual Report – Early proof

    Estimating market share and future earnings in such an environment is incredibly difficult. Historic growth cannot be a benchmark in a disruptive environment. The 2025 annual report, is an indication that he pivot is working.

    In million EUR2025 revenueYOY Revenue Growth2025 Adj EBITDA %2025 EBITDA
    Products77.737.6%20.9%16.2
    Services143.1-4.1%13.7%19.6

    The product segment grew 38% year-over-year with significantly higher margins than services. This is what the bull case needs – recurring, high-margin revenue replacing lower-margin billable hours.

    understanding the business

    Triforks organisation is a bit complex – The labs consists of minority owned (less than 50% stake) companies. While Triforks main business also consists of different business units. Both labs and the main business might sell products (SAAS) or hourly rates.

    Finally, this has some implications for the income statement – if Trifork sells a labs company this will affect the income statement – but if they buy a company it wont – also, income from labs does not go to the income statement – but any increase or decrease in book value will.

    trifork labs

    Arkyn Studios (44% ownership) is a “digital enterprise”. They help SAP customers organise maintenance and planning through the APPs: FastWork & FastPlan. Customers include Vestas, Arla, Porsche & Royal Unibrew.

    No data: ROA, Solvency & Income.

    *put formula used*

    AxonIQ (20% ownership) is the most adopted event sourcing framework in the Java ecosystem. Used in banking, retail, insurance, and government systems worldwide. he technology provides total operational control by literally “storing every decision” an IT system makes. While the basic framework is open-source, AxonIQ is the commercial extension that sells the high-margin central management servers required to run it at an enterprise scale.

    No data: ROA, Solvency & Income.

    Dawn Health (27% ownership) – Digital Therapeutics (DTx) and “Software as a Medical Device” (SaMD). Dawn Health’s value is its ISO 13485 certification and its ability to navigate clinical trials for software. They build FDA-approved and CE-marked software that is prescribed alongside traditional drugs (e.g., companion apps for insulin dosing or chronic disease management). Customers include massive players like Novo Nordisk and Novartis.

    ROA -77%. Solvency 80%. Income -52.217.000 DKK

    Solvency = (Equity*100)/Assets

    ROA = (Income*100)/Assets

    Frameo APS (6,1% ownership) – Is a software for those simple tablet looking devices, that can display pictures. Frameo is one of europes fastest growing companies (increased 10 fold over the last two years) – and it is very profitable. Frameo APS is almost the same size as Trifork.

    ROA 60%. Solvency 80%. Income 106.868.000 DKK

    XCI Holding (5% ownership) – Is a cyber intelligence firm – they help government agencies track down cyber criminals – using their extended platform/product. Income has grown steadily since 2021 and has increased five fold since then.

    ROA 50%. Solvency 98%. Income 52.171.000 DKK

    trifork trifork

    Trifork group consists of Trifork and Trifork majority owned companies.

    Ownerships on p147 & p151 annual report.

    Nine AS (ownership 90%) – Almost entirely public sector. Triforks biggest unit – with a Fairly big market share among Danish Government Agencies. The april 9 – Nine won a contract to deliver Danish Digital Wallet for the Danish Agency (Digital Government) worth 29.000.000 DKK. Nine has had a pretty big retraction in ROI which is down from the 40’ties in 2021-2023 – with income only slightly down.

    ROI 27,5%. Solvency 76,5%. 38.112.000 DKK

    Netic (ownership 88%) has developed the platform Contain – a cloud platform designed to develop and run big applications – with Netics own datacentres.

    ROI 11%. Solvency 28%. Income 12.795.000 DKK.

    Erlang Solutions (ownership 100%) – Erlang & Elixir programming language. Designed for zero downtime. Mostly consultancy/ programming services . *no numbers?*

    Trifork products solely under the Trifork brand includes:
    iFly4A – Modular application used by the crew to “duty schedules and flight info to checklists, documents, and peer-to-peer messaging – (…) customizable tools”. Customers includes …
    See more: https://trifork.com/aviation-app/

    Corax AI a workflow ai assistent – summarizes meetings, writes drafts for customer supports and chat bots. See more: https://trifork.com/boost-your-customer-service-with-ai-superpowers/

    Alon is a response to The EU Pay Transparency Directive. Its is an application that contributes with – Automate pay audits, Transparent pay ranges, Custom reporting & Fair pay recommendations.

    Tiris messenger is messaging platform for companies with strict GDPR regulation. It uses encrypted messages with sovereign datacentres.

    Sovereign AI as a service – is a another product being offered by Trifork. It is essentially a combination of Corax AI, Corax Data and Netic datacentres.

    A deeper dive into growth drivers & hinderes

    The pivot away from US tech conglomerates is a potential growth catalyst. In Trifork’s own words – “Danish public authorities are increasingly facing challenges related to dependency on a small number of large foreign technology providers and limited control over data and critical digital infrastructure” (annual report, 2025). It is the segment Netic that is most likely to take advantage of this. Note Netic earnings is about 2 million EUR (about 8% of Trifork earnings).

    While 8% of total earnings is minor – the addressable market for Netic is huge; managing the data within the European public sector. Crucially, the regulatory barrier to entry is valid. Though, resolving the issue surrounding the US CLOUD Act and European GDPR might completely strip away Netic’s potential – as their market disappears.

    Netic’s platform is being levered through most of Trifork Groups products – highlighting Triforks strategy of leveraging capabilities and synergies across business units. In some scale – making Trifork as an investment – a sovereign data play – as a wide range of Triforks products, differentiate on NIS2 and GDPR regulation.

    Valuation

    Traditional valuation methods struggle in a disrupted sector with a changing business model. Historic growth rates are unreliable as a benchmark. Analyst forward estimates are stale and might not account for AI disruption or the uncertainty of a mid-pivot business model – if it matters – they are projecting a PE under 10 by 2028. In short – assigning growth rates to Trifork is incredibly difficult.

    Trifork currently trades at a TTM PE in the low 20s – cheap in historical terms. This suggests the market has already discounted significant disruption risk. Note – this excludes about 10% of Triforks earnings, which is accounted on the balance sheet!.

    The product growth in 2025, is a key – as this is an early indicator that the pivot towards the software as a service is working. Though not conclusive. If the services-to-products pivot continues at anything close to the 2025 pace, earnings could grow substantially within three years – compressing the PE into single digits at today’s price.

    Relative PE & analyst estimates

    2025 -> 2028
    Trifork 22.9x 13.1x 9.89x 8x
    Netcompany 66.1x 20.5x 15.6x 13.4x
    Cbrain 52.1x 23.4x 15.3x 11.3x
    NNIT -51.3x 13x 8.31x 6.52x

    Triforks own guidance indicates severe mispricing – at a 2026 PE around 12,5 and 11. Assumed 50% income to EBITDA ratio. Guidance 35 to 40.000.000 EBITDA.

    Conclusion

    Can Trifork move away from what made it successful – agile, customer-first consultancy – toward a product-first mindset? The 2025 annual report suggests it can – while the market seems to not think so (no trust in that EBITDA guidance!). If the pivot holds, the upside across healthcare, data sovereignty, and aviation is substantial. The Trifork Investment case is essentially a bet on #1 a normalization in software consultancy #2 data sovereignty in EU as a catalyst towards high margin recurring revenue.

    Trifork since ipo

    2021-2022: Zero interest rate policy environment. High valuations, particularly in the LABS segment.

    2022-2023: Rising interest rates drove multiple compression and resulted in write-downs within LABS.

    2023-2024: Oversupply of developers (driven by Big Tech layoffs) and delayed IT investments due to higher interest rates and macroeconomic uncertainty. This triggered a collapse in operating income. When consultants aren’t billing hours, the bottom line takes a severe hit.

    2024-2025: The Service segment continues to face headwinds (declining 4%). A new product-oriented strategy is driving higher margins. Operating income is recovering to 2022 levels.

  • Valuation Rockwool

    Valuation Rockwool

    Introduction

    Rockwool A/S is a pure-play insulation giant currently trading around historic lows – largely driven by asset seizure by the Russian government. As the market is fixated on this one headwind, Rockwool still enjoys significant tailwinds, such as the Energy Performance of Buildings Directive (EPBD).

    The EPBD states that; “85% of buildings in the EU were built before 2000 and 75% have poor energy performance (…) Yet the annual energy renovation rate remains very low at 1%” (European Commission, 2026). This low hanging fruit, of increasing energy efficiency, is a driver for continued growth.

    Profitability & Valuation

    Rockwool currently has a 10-year and 5-year revenue CAGR of respectively 5,8% and 11,9% (Sheet, 2026).

    Furthermore, Rockwool had a 10-year and 5-year CAGR income growth of 13% and 28%, partly driven by increased profitability.
    – Ratios Illustrated underneath.

    (Marketscreener, 2026) (Sheet, 2026).

    These ratios are all stronger than competitors’, though attributable to differences in product mix. A proper comparison requires further details in profitability within glass and stone wool.

    Competitor ratio “analysis”:

    (MarketScreener, 2026) (Sheet, 2026).

    Kingspan trades at a PE at 19.3 and Saint-Gobain 13.5. Thus, Rockwool is trading at a discount to Kingspan and on par with Saint-Gobain. Note: Owens Corning is expecting a loss in 2025, but a 2026e PE at 12.2.

    Though analyst expectations for future growth creates a different picture:

    (MarketScreener, 2026) (Sheet, 2026).

    Finally, Rockwool trades at a 32% discount to their five-year average of 19.9 – Assuming a 2025e PE at 13.5.

    PE development:

    (Rockwool Russia, 2026) (MarketScreener, 2026) (Sheet, 2026).

    Rockwool continues to invest in capacity and optimizing operations – expressed by their high capex:

    (Marketscreener, 2026) (Sheet, 2026).

    Thus, Rockwool is essentially plowing all their earnings into new factories (Five-year average = 90%).

    Competitive advantages & MOATS

    Rockwool’s insulation products are enjoying moats – as traditional glass wool is combustible and thus prone to fires. This makes Rockwool the preferred choice in constructions such as timber and datacenters. While glass wool is a cheaper product, it also has a shorter lifespan – thus stone wool is essentially a quality product at a premium price.

    The asset seizure in Russia will contribute negatively to their earnings growth and margins. Some investors (and Rockwool) have been worried about giving a foreign company access to Rockwool technology – while this is a key risk, it might be overdone due to the logistics of insulation products. These voluminous products are on average transported for around 400 kilometers with no products crossing borders (Rockwool, 2025). This essentially creates a geographical moat while protecting against some geographical tensions such as tariffs.

    In general retail stores are in an attractive competitive situation, as they have more leverage to demand a lower price from suppliers. This might pressure margins in the longer terms, depending on Rockwool’s pricing power and channel management. Strong brands and quality products, demand better terms for negotiating prices – though, I cannot estimate the development of Rockwool and competitor’s product development – But, Saint Gobain (Isover) has developed a chemically engineered glass wool product that is lighter, cheaper and fire resistant – but on the downside more fragile and less soundproof.

    Finally, it is capital intensive to build the factories that make stone wool and further energy intensive to produce stone wool. Expenditures serve as a moat, as the high upfront costs serve as barriers to entry.

    Rockwool products

    Rockwool’s product mix is collected in two segments – insulation (79% of revenue) and systems (21% of revenue) (Rockwool, 2025, pp 17). Both segments are operating at an EBIT margin of 14-15% (Rockwool, 2025, pp 26). Insulation is insulation (stone wool) and systems are: Rockfon (panels for acoustic), Rockpanel (façade panels), Grodan (for roots, agriculture) & Lapinus (additive for brake pads etc.). The size of the business unit is in respective order (Rockwool, 2025, pp 21).

    Conclusion

    I expect Rockwool to be an attractive investment, largely attributable to its MOATS and sector-wide tailwinds. Furthermore, companies with such a strong track record and profitability often cost pe 20+. 

    This valuation can likely be attributed to short-term headwinds (asset seizure) and low analyst expectations for near-term earnings growth.

    This investment is a textbook example:
    – Double digit earnings growth
    – Low debt
    – Strong and expanding margins (though a small setback is expected)
    – Solid tailwinds (…)
    – Shareholder friendly

    Though risks persist:
    – Vulnerability to energy supply (regulation)
    – Product engineering from competitors (Isover Ultimate)
    – High depreciation of assets requires continuous investments in factories (overlooked in the price to earnings ratio)

    Disclaimer

    I am heavily invested in Rockwool, at around 21% of my total portfolio. I can have made mistakes. I am not a licensed financial advisor. I cannot advocate for investing in this company.

    Mental Notes / Future research

    Price elacity of Rockwool products from high salaries in construction? One Up Wallstreet states need for continuos investments as unfavourable. Need stronger comparison of competitors (Kingspan & Isover especially). Estimation of growth based on factory expansion and new factory construction (as i recall from earningscall there are 6 projects on the way).

    Sources

    Sheet, 2026:

    MarketScreener, 2026: https://www.marketscreener.com/

    European Commision, 2026: https://energy.ec.europa.eu/topics/energy-efficiency/energy-performance-buildings/energy-performance-buildings-directive_en

    Rockwool, 2025: https://www.rockwool.com/siteassets/investors/financial-reports/2025/annual-report-2024.pdf

    Rockwool Russia, 2026: https://tools.eurolandir.com/tools/Pressreleases/GetPressRelease/?ID=7874390&lang=en-GB&companycode=dk-rock&v=

  • Short Form Rockwool

    Short Form Rockwool

    INTRO

    Rockwool is a Danish pure-play insulation conglomerate. The stock is currently depressed by macroeconomic headwinds and recent seizure of its Russian assets.

    STRATEGY & MARKETING

    The stone-wool market has high barriers to entry due to capital intensity. Rockwool is vertically integrated, mitigating reliance on suppliers. Rockwool is gaining market share, driven by superior performance compared to traditional glass-wool. The superior performance comes from fire safety standards and product longevity. It is not unlikely, that increased timber constructions and data centers, are going to be growth drivers in US in the short term, while re-insulation regulation and reconstruction of Ukraine are “going to be” European drivers.

    VALUATION

    Rockwool is priced at a earnings yield of 7,5% Well bellow historical averages. Though, “on par with peers”. Rockwool has a strong profitability expressed by:

    Return on non current assets = 21%, Return on revenue = 14%.

    And a strong balance sheet expressed by:

    Liabilities/Assets = 20%, Income/Liabilities = 69%.

    Furthermore, assets contain barely any intangibles such as goodwill. Finally, the high earningsyield should be seen in light of also high earnings-growth, driven by margin expansion & revenue-growth. .

    10 year compound earnings growth at 20%, 10 year compound revenue growth at 6%.

    CONCLUSION

    Rockwool is a “Quality” company trading at a “Value” price. While the construction cycle is unpredictable, the Russian risk is now realized and likely priced in. Thus, the current valuation likely offers a significant margin of safety.

  • Update Pandora

    Update Pandora

    Pandora’s unaudited Q4 2025 earnings have triggered immediate caution across the market. The report reveals a softening US consumer and a sharp 7% decline in like-for-like growth across Latin America. Against a backdrop of rising tariffs and silver price volatility, the investment community has predictably fixated on a single metric: the potential erosion of EBIT margins. However, while valid, this financial anxiety overlooks a far more fundamental risk regarding whether Pandora can deliver on its marketing strategy to secure growth in both new and existing markets.

    The current strategic direction raises existential questions for a brand defined by “affordable luxury.” There is genuine scepticism as to whether jewellery with reduced silver content will satisfy the brand’s core demographic, or if these consumers will tolerate price hikes driven by tariffs and input costs. A prudent marketing manager would rightly fear that allowing external cost pressures to dictate pricing and product composition risks decoupling the brand from customer needs. The danger is that Pandora’s new lineup reflects its own supply chain constraints rather than what its customers actually want.

    Disappointingly, the initial communications from the new CEO, Berta de Pablos-Barbier, fail to address this demand-side peril. By stating a focus on “navigating the current market environment” and “reducing commodity exposure,” the leadership appears prioritized on defensive financial engineering rather than offensive market conquest. The vague commitment to “course-correct in select areas” lacks a clear strategy for arresting market share loss or reigniting brand appeal in struggling regions.

    I argue that the winning strategy lies in a fundamentally different approach: Pandora should be willing to accept margin compression in the near term to fund a massive expansion in marketing expenditures. In a fragmented global market—particularly in regions like Latin America—the priority must be acquiring customers and deepening brand equity. Sacrificing short-term profitability to solidify a competitive moat is the surer path to long-term earnings growth, ensuring Pandora remains the dominant player in affordable jewellery rather than a retailer protecting margins on shrinking volume.

    Source: https://pandoragroup.com/investor/news-and-reports/company-announcements/newsdetail?id=27746

  • Valuation Rio Tinto

    Valuation Rio Tinto

    Rio Tinto (RIO.L) presents a compelling case of low valuation, historic high growth, and a structurally interesting market. It is using its massive cash flows from iron and steel to diversify into the “metals of the future”: Lithium, Aluminium, and Copper.

    The core investment thesis rests on a structural reality: It has never been harder to build a mine. The easy-to-access ore bodies have already been mined, forcing the industry to seek resources in deeper, more complex, or politically unstable geographies. Simultaneously, increasing regulatory pressure has extended development timelines by years, if not decades. While this drastically increases the time before capital expenditures can be covered, it also serves as a formidable “barrier to entry” that mitigates the risk of new competitors.

    In this environment, a company’s “social license to operate” becomes its most critical asset—and its biggest risk. The industry is inherently dirty, and stakeholder pushback is tangible. This was exemplified when Rio Tinto’s Jadar lithium project in Serbia was dropped due to local protests, and it is currently visible in the environmental concerns surrounding the massive iron mine in the rainforests of Central Africa. These examples highlight that while the demand for metals is soaring, the supply response is constrained by the sheer difficulty of execution.

    Despite high profitability and earnings growth, the valuation remains cheap. This is primarily driven by the risk of cyclical cash flows; as metal and mineral prices are highly correlated with macroeconomic development, a downturn in the economy will lead to a significant drop in earnings. However, the stock’s positive correlation with interest rates might help decrease overall portfolio risk, providing balance when interest-sensitive assets (such as investments with cash flows far out in the future and/or high debt) struggle.

  • Pandora

    Pandora

    Pandora (PNDORA) is a Danish jewelry conglomerate uniquely positioned as the global leader within the “affordable jewelry” space. It represents an exciting investment case due to its significant competitive advantages and plausible growth trajectory.

    Competitive Advantages As the largest player in the sector, Pandora wields a massive data advantage that optimizes both production and customer targeting. It creates a powerful flywheel: high “top-of-mind” awareness among consumers signals strong brand equity and a successful marketing strategy (though the key challenge remains converting this awareness into purchase intention).

    This scale drives not only cost efficiencies but also quality control. By owning massive production facilities in Thailand—and soon Vietnam—Pandora benefits from vertical integration. Controlling the supply chain makes the business far more resilient than competitors who rely on outsourcing.

    Strategy & Positioning Pandora is positioning itself to win with Gen Z through sustainability initiatives, including the use of 100% recycled silver and gold and the rollout of lab-grown diamonds. However, the reliance on influencer/popstar marketing (earned media) carries inherent risks. As with most fashion players, maintaining positive brand perception is the company’s most significant vulnerability.

    Growth is expected to come from two avenues: entering new geographic markets and expanding product categories, as Pandora transitions from a charm-maker into a “full jewelry brand.”
    Though another avenue is through consolidation of the jewellery market and market penetration (market development).

    Valuation & Risks The stock market currently appears overly fixated on macroeconomic headwinds: tariffs, a falling USD, and soaring gold/silver prices. In our opinion, these fears are exaggerated. While these factors may impact short-term profitability, Pandora has proven levers—such as adjusting value chains and raising prices—to combat them. The strategic struggles in China, however, represent a more genuine structural threat – whereof some markets has been showing little interest in Pandoras value proposition – signalling that Pandoras product mix, is not a “one size fits all”, but instead is limited by cultural appeal.

    Financially, while the company carries a relatively high liabilities-to-assets ratio, its ability to service this debt (income-to-liabilities) remains healthy. Management continues to signal confidence through an aggressive capital allocation policy, primarily in the form of share buybacks.

  • AI analysis Rockwool

    AI analysis Rockwool

    Rockwool A/S (ROCK.B), the global leader in stone wool insulation, currently presents one of the most compelling yet complex investment cases in the European industrial sector. Trading at a Price-to-Earnings ratio of approximately 14-15x, the company is valued at a significant discount to its historical trading range and its high-quality peers. 

    MultipleStrategy posits that the market has inefficiently priced the “Russia Risk” and the cyclical fear of a US recession, while failing to adequately capitalize the structural tailwinds emerging from the European Union’s Energy Performance of Buildings Directive (EPBD) and the latent potential of Ukraine’s reconstruction.

    Our analysis, grounded in a review of financial data spanning 2015-2025 and comparative peer benchmarking, reveals a company with a strong balance sheet—characterized by a Liabilities-to-Assets ratio of just 21% and an Income-to-Liabilities ratio of 68,58%, vastly superior to peers like Saint-Gobain and Owens Corning. Furthermore, Rockwool’s gross margins, averaging 67%, indicate a pricing power and vertical integration advantage that is structurally distinct from the broader building materials sector.

    While the consensus view fixates on the cyclical downturn in new residential construction, this report argues that Rockwool is transitioning into a growth phase driven by regulation (re-insulation) and reconstruction of Ukraine. The “Deep Value” thesis is supported by a disparity between the company’s 10-year EPS CAGR of 19% and its compressed valuation multiple. 

    MultipleStrategy provides an exhaustive examination of these dynamics, segmented into strategic analysis and valuation modeling.

    1. Company Overview and Competitive Moat

    1.1 The Physics of Stone Wool: A Technical Moat

    To understand Rockwool’s financial resilience, one must first appreciate the physical properties of its core product. Stone wool is not merely “insulation” in the commoditized sense; it is a complex substrate derived from melting volcanic basalt rock at temperatures exceeding 1,500°C. Unlike its primary substitutes—glass wool (silica-based) and plastic foams (petrochemical-based)—stone wool possesses a unique trifecta of properties: thermal resistance, acoustic absorption, and, most critically, non-combustibility.

    In the regulatory landscape, fire safety has moved from a “nice-to-have” to a “license-to-operate” parameter. Plastic foam insulations, while thermally efficient, are combustible. Stone wool, being essentially rock, does not burn. This physical characteristic creates a regulatory moat. As building codes in the EU and North America tighten to mandate non-combustible materials in high-rise and public buildings, Rockwool effectively gains a monopoly-like position in these sub-segments, shielding it from price wars with cheaper foam alternatives.

    1.2 Manufacturing Intensity and Barriers to Entry

    The production of stone wool is capital and energy-intensive, requiring massive furnaces or melters. This capital intensity, often viewed by the market as a drag on Return on Invested Capital (ROIC), actually serves as a formidable barrier to entry. While a foam insulation plant can be stood up with relatively low capital expenditure (CapEx), a stone wool facility requires hundreds of millions of Euros and years of permitting. Furthermore, this restricts supply elasticity; new competitors cannot easily enter the market to erode margins during upcycles.

    Rockwool’s strategic pivot toward decarbonizing its production—replacing coal-fired furnaces with biogas and electric melters (as they have done in Swiss and Norwegian factories)—increases moat through know-how or manufacturing capabilities. By lowering the embodied carbon of its product, Rockwool aligns itself with the “Scope 3” reduction targets of major real estate developers, becoming a preferred supplier for green-certified buildings (LEED, BREEAM).

    1.3 Systems; Productmix

    While the Insulation segment drives 79% of revenue, while the Systems segment provides 21% of revenue. The systems segment consists of: 

    • Rockfon: High-end acoustic ceiling solutions. This business benefits from the trend toward open-plan offices and noise reduction regulations in schools and hospitals. It commands premium pricing due to aesthetic and functional differentiation.
    • Grodan: Horticultural substrates. As global agriculture shifts toward hydroponics to conserve water and fertilizer, Grodan provides the stone wool substrate for precision growing. This business is less correlated with the construction cycle and more aligned with food security trends.
    • Rockpanel: Cladding boards made from compressed stone wool. This product competes directly in the façade market, offering architects design flexibility with the fire safety of stone.
    • Lapinus: Engineered fibers for friction materials (brakes), gaskets, and coatings. This is a highly specialized industrial application with high switching costs for customers.

    The Systems segment typically delivers higher margins and ROIC than the Insulation segment, and its growth acts as a buffer against construction cyclicality.

    2. Strategic Segment: Macro-Triggers and Geopolitical Risks

    The investment thesis hinges on triggers like re-insulation, peace in Ukraine, and risks like Russian seizure and global recession. This section deconstructs these elements with granular detail.

    2.1 The Re-Insulation Super-Cycle

    The Energy Performance of Buildings Directive (EPBD) is the most significant regulatory tailwind in Rockwool’s history, yet it remains underappreciated by the broader market. Adopted in May 2024, the revised EPBD mandates that EU member states reduce the average primary energy use of residential buildings by 16% by 2030 and 20-22% by 2035. 

    https://energy.ec.europa.eu/topics/energy-efficiency/energy-performance-buildings/energy-performance-buildings-directive_en

    The Opportunity:

    85% of buildings in the EU were built before 2000 and 75% have poor energy performance. Yet the annual energy renovation rate remains very low at 1%.

    • Renovation vs. New Build: In a high-interest-rate environment, new construction (mortgage-dependent) slows down. However, renovation is often subsidized by government grants (e.g., Italy’s Superbonus, Germany’s KfW programs) or enforced by regulation. This provides a counter-cyclical hedge.
    • 2026 Catalyst: Member states must submit their National Building Renovation Plans (NBRPs) by December 2025/2026.4 As these plans are publicized and subsidies are codified, we expect a surge in forward orders for insulation materials, likely beginning in late 2025. This creates a foreseeable demand ramp that is currently excluded from short-term consensus estimates.

    2.2 Ukraine Reconstruction: The Logistics of a Marshall Plan

    The reconstruction of Ukraine represents a massive, albeit binary, potential demand shock. The devastation of housing stock, industrial facilities, and infrastructure in Ukraine is extensive. The World Bank and other institutions estimate reconstruction costs in the hundreds of billions.

    Rockwool’s Strategic Position:

    Rockwool is uniquely positioned to service this demand due to its geographical footprint. Insulation is voluminous and expensive to ship. Rockwool operates factories in Cigacice and Malkinia (Poland) and Ploiesti (Romania), directly bordering Ukraine This proximity can give Rockwool a logistical cost advantage. Though competitors have started construction of factories close to Ukraine. Kingspan for example has announced a €280 million investment to build a “Building Technology Campus” in Ukraine, aiming to manufacture advanced insulation and district heating solutions locally and Saint-Gobain has also moved early, opening a gypsum mix factory in 2024

    https://www.ukrainerebuildnews.com/saint-gobain-opens-first-factory-in-ukraine-to-make-60-000-tons-a-year-of-gypsum-mixes

    Baker McKenzie Advises Kingspan Group on State-of-the-Art EUR 280 Million Building Technology Manufacturing Campus in Ukraine | Newsroom | Baker McKenzie 


    Thus when the war ends Rockwool can supply from Polish/Romanian factories to meet urgent reconstruction needs – and in the longer-term reinvest in local capacity, leveraging its previous market knowledge (Rockwool had a significant market share in Ukraine pre-war).

    To summarize, the reconstruction of Ukraine is unlikely to boost earnings through volume but might through supply-demand metrics and as we will mention later would likely compress the risk premium on Rockwool’s stock, leading to multiple expansion. This is a double edge sword, since if supply from competitors catches up, before the demand from rebuilding Ukraine increases it could create excess supply. 

    2.3 The market penetration strategy in US

    Global recession is a risk given interest rates affect construction. However, Rockwool’s North American strategy is one of market penetration.

    This is because Rockwool’s market share in North American residential insulation is relatively low compared to fiberglass giants like Owens Corning. This means Rockwool can grow by taking share (substitution) even if the total pie shrinks. The driver for this substitution is, again, fire safety and moisture resistance, particularly in the growing segment of timber-frame construction and rainscreen façades.

    Furthermore, a significant portion of Rockwool’s US growth comes from non-residential sectors. The explosion of data center construction (AI-driven) requires massive amounts of fire-safe, thermal management materials. Rockwool’s products are standard-spec for many hyperscale data centers. Additionally, the re-shoring of manufacturing (chip fabs, battery plants) supported by the CHIPS Act and IRA drives demand for technical insulation (process pipes, high-temperature applications).

    2.4 The Russia Risk: A Forensic Analysis

    Russian asset seizure is the single largest overhang on the stock. Rockwool operates four factories in Russia. Management has steadfastly refused to voluntarily exit, citing the risk of handing over dual-use technology and assets to the Russian regime.

    The Legal Threat (Decree 693 & 442):

    In 2024 and 2025, the Kremlin escalated its economic warfare. Decree 442 establishes a mechanism to seize assets of “unfriendly” foreign entities to compensate for frozen Russian sovereign assets abroad.15 Decree 693 facilitates the rapid sale of such seized assets.16

    Unlike consumer brands (e.g., Starbucks, McDonald’s) that could shut down shops, Rockwool’s assets are heavy industrial plants. If seized, they would likely be transferred to a Russian competitor (like TechnoNICOL), who would immediately gain capacity and technology free of charge.

    Financial Exposure:

    While Rockwool does not disclose exact Russian profitability, analysis of segment data suggests the Russian business is highly profitable due to sunk capital costs and localized raw materials. We estimate Russia contributes 10-15% of Group EBIT.

    • The Risk Scenario: If Putin nationalizes these assets, Rockwool would face an immediate write-down of book value (approx. €200-400m) and a permanent loss of that earnings stream.
    • The Valuation Implication: The current low P/E of 14x suggests the market has already largely discounted this earnings stream. In a perverse way, the actual seizure might be a “clearing event,” removing the uncertainty and the ESG stigma (NACP “Sponsor of War” list) that prevents many institutional funds from owning the stock. Once the assets are gone, the “Russia Risk” is zero, potentially allowing the remaining “Clean Rockwool” to re-rate to a higher multiple.

    3. Financial Analysis: Dissecting the Data

    This section integrates the specific data points provided in the user’s images (Image 1 and Image 2) to build a robust financial profile.

    3.1 Balance Sheet Analysis (Image 1 Integration)

    The comparative data provided in Image 1 reveals a stark contrast in capital structure between Rockwool and its peers.

    Table 1: Financial Health & Efficiency Ratios (Nov 2025 Data)

    MetricRockwoolSaint-GobainOwens CorningKingspan
    Liabilities / Assets21%58%64%53%
    Income / Liabilities69%8%7%13%
    Gross Profit / Revenue67%28%17%30%
    Operating Income / Revenue18%11%15%10%
    Income / Revenue14%6%6%8%

    Insights from Image 1:

    1. Strong Balance Sheet: Rockwool’s Liabilities/Assets ratio and income/liabilities is extraordinarily low compared to the range of its peers. In a higher than anticipated interest-rate environment (2024-2025), this is a massive competitive advantage. This provides Rockwool with financial and strategic maneuverability. 
    2. Gross Profit/Revenue of 67%. Saint-Gobain (28%) and Owens Corning (17%) operate with much thinner gross margins.
    • Why? This reflects Rockwool’s vertical integration and the nature of stone wool. The raw material (rock) is cheap and abundant; the value add comes from the technology of melting and spinning. Owens Corning’s lower margin reflects the higher input cost of silica/glass and potentially a more commoditized product mix in roofing. Saint-Gobain acts partly as a distributor, which naturally dilutes margins. Rockwool’s 67% gross margin indicates immense pricing power—it sells a premium technical product. 

    3.2 Historical Performance Trajectory (Image 2 Integration)

    Image 2 provides a longitudinal view of Rockwool’s performance, essential for verifying the “Growth” aspect of the thesis.

    Table 2: Historical Growth Metrics (CAGR Analysis)

    Metric10-Year CAGR5-Year CAGRAnalysis
    Revenue5.68%11.67%Growth is accelerating. The 5Y CAGR is double the 10Y, driven by price increases and North American expansion.
    EPS19.20%16.56%EPS growth consistently outpaces revenue growth. For every 1% of sales growth, Rockwool generates ~3% of EPS growth.
    Equity PS8.63%8.48%Steady compounding of book value, even after significant dividend payouts and buybacks.

    4. Valuation Analysis

    4.1 Relative Valuation: The Peer Disconnect

    • Rockwool (ROCK B): 2025 P/E ~15.0x. P/Equity 1.9x.
    • Kingspan (KRX): 2025 P/E ~20.2x. P/Equity 2.9x.

    Kingspan trades at a 33% premium to Rockwool (20.2x vs 15.0x).

    • The spread is unjustified based on fundamentals. It is largely a geopolitical discount (Russia) and a “capex intensity” penalty. 

    4.2 Historical Valuation Regression

    Looking at Rockwool’s own history 

    • 2015-2020: Average P/E ranged from 18x to 25x.
    • 2023-2025: P/E compressed to 11x to 15x.

    However, EPS has continued to grow (CAGR 19%). This divergence between price (valuation) and value (earnings) is the classic definition of a value investment opportunity.

    (CompaniesMarketCap.com)

    5. Conclusion and Investment Verdict

    Work in progess

  • Bandai Namco

    Bandai Namco

    Ticker: (7832.T). Not financial advice.

    Strategy

    Bandai Namco’s positioning is particularly compelling due to its ability to leverage franchises across games, toys, amusement parks etc. By monetizing IP through multiple formats, the company builds an integrated ecosystem that extends the lifecycle and economic value of each franchise. This structure creates meaningful moats, as success depends not on a single hit product but on coordinated execution across several categories.

    The primary risk is competition, particularly from rights holders such as Shueisha, which has stated ambitions to capture more value from its own franchises. However, partners like Shueisha lack the operational capabilities required to replicate Bandai’s model independently, as publishing, game development, and large-scale product commercialization rely on distinct and non-transferable skill sets. While competition remains a structural feature of the entertainment industry, franchise-driven ecosystems provide durability in margins and customer engagement.

    Multiples

    Bandai Namco is currently trading at a P/E of 24.4, representing a 12.6% discount to its five-year historical average and a 10% discount to peers. This multiple does not reflect first-half results, which indicate a modest increase in earnings. Assuming a long-term earnings CAGR of 10–14%, the implied annual return ranges from 12.7% to 20.2%, based on a 10% discount rate and an exit multiple of 24 under a continuous growth assumption. Over the past ten years, Bandai has delivered a CAGR of approximately 14%

    From a balance sheet and profitability perspective, Bandai Namco maintains low leverage and strong margins, broadly in line with peers.

    Bandai multiples:

    Liabilities/Assets28,01%
    Income/Liabilities42%
    Income/Revenue10,39%
    Income/Assets11,70%
    Income/Non Current Assets32,41%

    Notable mentions:

    • Kadokawa may increasingly pursue in-house game publishing rather than relying on Bandai Namco, which could reduce Bandai’s access to third-party IP over time.
    • A significant share of Bandai Namco’s IP exposure is tied to the anime segment, making parts of its growth dependent on continued demand within this category.
    • The current P/E multiple is partially influenced by the exceptional success of Elden Ring; as expectations normalize and release-related hype fades, reported growth and valuation metrics may compress.
    • The japanese yen (as illustrated vs the euro beneath).

    What MultipleStrategy thinks

    While Bandai Namco currently trades at an attractive valuation with strong profitability, structural risks to its Digital Business are emerging. The company relies heavily on licensing major IPs from media giants like Shueisha and Kadokawa—partners increasingly signaling intent to capture more value in-house.

    Signs of this shift are already visible. Kadokawa’s subsidiary, FromSoftware, recently reclaimed sole trademark rights for Elden Ring, indicating potential self-publishing of future blockbusters. Shueisha has launched Shueisha Games to develop indie titles internally, potentially still leaving room for Bandai Namco’s AAA studios.

    If these IP holders increasingly bypass Bandai Namco, the Gaming segment—responsible for a substantial portion of high-margin revenue—faces significant pressure. In contrast, the Toys & Hobby division remains protected by a moat of manufacturing and branding competencies, insulating it from similar disruption.

    In short, Bandai Namco remains a solid investment if it can maintain market share in its Digital Business, assuming continued global adoption of anime.

    ***Should mention:
    Bandai Namco owns Tekken & Gundam.
    – An older but relevant table illustrating margins and market caps across peers:

    Note: Square Enix is affected by one time effects.

  • Can Match Group Revive the Online Dating Market?

    Can Match Group Revive the Online Dating Market?

    Updated version: https://multiplestrategy.com/2026/04/22/match-group-update/

    Ticker: MTCH. Not financial advice.

    Match Group has negative equity, and half of their assets consist of goodwill. Their MAU (Monthly Active Users) has been declining since 2022. Furthermore, Match Group acquired HyperConnect in 2021 at what appears to be an overly optimistic price, leading to massive write-downs.

    Match Group recently changed their CEO (among other leadership changes), and as he stated during the Q2 earnings call: “Tinder needs a lot of work. It has grown stale because of short term monetization & lack of innovation.” Additionally, there is a general slowdown in the online dating market, and indications suggest Bumble has captured market share from them – along with other and more niche dating apps.

    On the other hand, Match Group has a reasonably profitable business, with an adjusted income / non-current assets ratio of 19% and an adjusted earnings / revenue margin of 17%. Furthermore, the new CEO intends to focus on making the company more agile, partly by laying off 20% of managers and reducing team sizes; he also plans to increase focus on product development. Established dating companies like Tinder and Bumble benefit from strong network effects.

    Even with Match Group’s negative equity and high proportion of goodwill, they are executing significant share buybacks amounting up to 130% of adjusted earnings. This can be explained by a ( long-term debt / interest expense ) of 2.4% and an adjusted earnings yield of 6.9%—in other words, low interest expenses and a low valuation (earnings per share relative to share price). This indicates a shareholder-friendly and aggressive capital allocation strategy that also suggests management believes the company is attractively priced.

    But – Match Groups debt ratio is simply too high, to justifying big share buybacks. While aggressive capital allocation is appreciated, the overall health of the company should come first. This is especially true since Match Groups refinancing could be coming in at higher interest rates. Furthermore stagnating revenue increases business risk which further increases cost of capital.

    I assume – The online dating market will continue to grow in the long term, following a normalization in MAU after a period of rapid expansion.

    Conclusion

    Match Group represents a high-risk turnaround case. While the company benefits from significant scale, network effects, and valuable user data, it faces major headwinds from elevated leverage, refinancing risks, and uncertainty regarding both execution and market development. Although the current valuation reflects many of these concerns, long-term success depends entirely on management’s ability to restore earnings growth and improve the value perceived by customers.

    Notable mentions:

    – User sentiment across the industry is historically poor, driven by a persistent perception that dating apps profit from keeping users single. The new CEO has signaled a strategic shift toward brand health, stating, “I would take a positive word of mouth over a $15 subscription any day.” This marks a critical potential pivot from short-term extraction to long-term value.

    – Interest expenses decreased in 2025, due to refinancing at a lower but stable interest. Decreasing the overall refinancing risk. Interest expenses should be higher in 2026, as there was a longer period in 2025 between paying off loans and settling new loans (Q3 2025). And liabilities/assets increased.

    – Match Group’s declining MAU stems from the Evergreen segment and Tinder, whereas Hinge is experiencing impressive growth.

    – Match Group has a adjusted earnings / (liabilities + goodwill) ratio of 8%.